Beautiful Louisiana style home with classic architectural details, seen on a bright and sunny day, hinting at the value of...

An Investor’s Take: Calculating the Long-Term ROI of High-Impact Siding vs. Lower Insurance Premiums in Louisiana

An Investor’s Take: Calculating the Long-Term ROI of High-Impact Siding vs. Lower Insurance Premiums in Louisiana

For any Louisiana homeowner or property investor, the calendar brings a familiar sense of dread. As summer approaches, so does the annual anxiety of hurricane season, coupled with the recurring shock of ever-increasing insurance premiums. It feels like a constant financial battle against the elements, forcing you to make tough decisions to protect your assets.
A beautiful Louisiana style home with classic architectural details, seen on a bright and sunny day, hinting at the value of protecting the property.

You know you need to fortify your property, but this leads to a critical question: is a five-figure investment in high-impact siding a smart financial move, or is it just an expensive upgrade with a slow, insignificant return? It’s a classic dilemma—spend big now to potentially save smaller amounts over time.

This article goes beyond a simple “pros and cons” list. We’re putting on our investor hat to provide a clear, step-by-step framework for calculating the long-term Return on Investment (ROI). We will break down the numbers to help you decide if high-impact siding is a justifiable expense or a money pit for your Louisiana property.

Key Takeaways

  • A Strategic Investment: In Louisiana, high-impact siding should be viewed as a strategic investment in risk mitigation and asset protection, not merely a cosmetic upgrade.
  • Beyond Simple Payback: A true ROI calculation must look beyond the simple payback period from insurance savings. It must include increased resale value, reduced maintenance costs, and the critical financial benefit of avoiding a named-storm deductible.
  • Data is Non-Negotiable: The key to an accurate analysis is gathering hard numbers before you commit. This means getting multiple, all-inclusive quotes for the siding installation and calling your insurance agent to get a firm quote on your new, lower premium.
  • The Deductible Wildcard: Avoiding a single major claim after a hurricane can make the entire siding investment profitable instantly. A typical named-storm deductible can easily exceed $10,000, completely changing the financial equation.

The Two Sides of the Equation: High-Impact Siding vs. High Insurance Premiums

To make an informed decision, you first need to understand the true costs and benefits of each side of this financial ledger.

Understanding High-Impact Siding: More Than Just a Pretty Face

High-impact siding is a category of exterior cladding engineered to withstand significant force from wind-borne debris and severe weather. This typically includes products like fiber cement siding (the most common type, pioneered by brands like James Hardie) and certain fortified vinyl products designed and installed to meet stringent building codes. Its “impact-resistant” quality comes from a combination of durable materials and specific installation methods that create a resilient shield for your home.

The Upfront Cost
There’s no sugarcoating it: this is a significant capital expenditure. A full, professional siding replacement in Louisiana can range from $15,000 to $35,000 or more, depending on the size of your home, the material chosen, and the complexity of the job. This figure is the Initial_Investment in our ROI calculation.

The “Hidden” Benefits
Beyond storm protection, this investment offers other tangible returns:
A close-up, detailed shot of modern fiber cement siding on a home, showcasing its clean lines, texture, and durable appearance.

  • Enhanced Curb Appeal: New siding dramatically improves a property’s appearance, which directly impacts its market value.
  • Lower Maintenance: Unlike wood siding that requires frequent scraping and painting, fiber cement is famously low-maintenance, resisting rot, pests, and the brutal Louisiana humidity.
  • Superior Durability: It stands up to the intense sun, heat, and moisture that can quickly degrade lesser materials.

Deconstructing Louisiana’s Insurance Premiums: Why You’re Paying So Much

If you own property in Louisiana, you’re already painfully aware of the high cost of homeowners insurance. Premiums in the state are among the highest in the nation, and for good reason.

The “Louisiana Factor”
Insurers set rates based on risk, and Louisiana is a textbook high-risk market. The primary drivers include:

  • Hurricane Frequency: The state’s position on the Gulf of Mexico makes it a frequent target for tropical cyclones.
  • Recent Storm History: A string of devastating storms in recent years has resulted in billions of dollars in claims, causing many insurers to raise rates, pull out of the state, or go insolvent.
  • Named Storm Deductibles: Most policies include a separate, much higher deductible for damage from a named storm, often calculated as 2% to 5% of your home’s total insured value.

Wind Mitigation 101
This brings us to the concept of wind mitigation. Insurance companies aren’t giving discounts out of kindness; they are offering a financial incentive for you to reduce their risk. By strengthening your home’s “building envelope”—the roof, windows, doors, and siding—you make it less likely that they will have to pay out a catastrophic claim. A stronger roof is a key part of this strategy, as it’s the first line of defense against Gulf South weather.

The Potential Savings
Installing certified, impact-resistant siding is a major wind mitigation upgrade. It signals to your insurer that your property is a lower risk. This can lead to significant, tangible discounts on your annual homeowners insurance premium. This discount is the Annual_Savings in our ROI calculation.

The Investor’s Playbook: How to Calculate Your Siding ROI

A smart investor never relies on guesswork. Let’s gather the specific data you need to run the numbers for your own property.

Step 1: Determine Your All-In Installation Cost

Your first task is to find out exactly what this project will cost.

An investor or homeowner sits at a wooden table with a calculator and blueprints, carefully planning a home renovation investment.

  • Action Item: Get at least three detailed, written quotes from reputable, licensed, and insured contractors in Louisiana.
  • What to Ask For: Ensure the quote is “all-in.” It must include the total cost for materials, labor, the removal and disposal of your old siding, any necessary permits, and a thorough cleanup.
  • Your Number: The final, averaged figure from these quotes is your Initial_Investment_Cost.

Step 2: Quantify Your Insurance Savings

This is the most critical step and requires a five-minute phone call. Do this before you sign any contract.

  • Action Item: Call your current insurance agent.
  • The Magic Question: Tell them, “I am considering installing [specific type/brand] of high-impact siding that is certified for wind and impact resistance. If I complete this upgrade, what would my exact new annual premium be?” Get the answer in writing if possible.
  • Your Numbers:
    • Current_Annual_Premium
    • Projected_New_Annual_Premium
    • Calculate your Annual_Insurance_Savings (Current_Annual_Premium – Projected_New_Annual_Premium).

Step 3: Factor in the “Soft” Financial Gains

An investor knows that returns come in many forms. Don’t overlook these crucial financial benefits.

  • Maintenance Savings: How much do you currently spend on maintaining your siding? If you have wood siding, a professional paint job can cost $5,000-$10,000 every 7-10 years. That’s an effective annual cost of $500-$1,400 you would no longer have to spend.
  • Increased Resale Value: High-quality exterior upgrades offer one of the best returns at resale. According to the 2023 Remodeling Cost vs. Value Report, a fiber-cement siding replacement in the West South Central region (which includes Louisiana) recoups an impressive 88.5% of its cost upon sale. This is a massive part of your long-term ROI.
  • Repair Cost Avoidance: This is the wildcard. While you can’t predict a storm, you can plan for the risk. Avoiding a single instance of having to replace a wall of wind-damaged siding—and paying your deductible to do so—is a huge financial win.

Putting It All Together: A Real-World Louisiana Calculation

Now that you have your numbers, let’s plug them into two common ROI models to see the full picture.

Model 1: The Simple Payback Period

This model is straightforward but often misleadingly pessimistic. It only answers one question: “How long until the insurance savings alone pay for the siding?”

  • Formula: Initial_Investment_Cost / Annual_Insurance_Savings = Payback_Period_in_Years
  • Example:
    • Siding Cost: $25,000
    • Annual Insurance Savings: $1,000
    • Calculation: $25,000 / $1,000 = 25 years

Investor’s Take: Seeing a 25-year payback period would cause most people to abandon the idea immediately. However, this calculation is fundamentally flawed because it ignores all other financial returns. It’s a poor tool for analyzing a long-term asset.

Model 2: The True 10-Year Investor ROI

This is a more holistic and realistic calculation that treats your home like a long-term asset. It accounts for all the financial gains over a typical holding period.

The strong, resilient exterior of a modern coastal home designed to withstand the elements, shown under a clear blue sky.

  • Example Scenario (Holding the property for 10 years):
Cost/Benefit Category Calculation 10-Year Value
Initial Investment Cost (From Contractor Quotes) ($25,000)
Total Insurance Savings $1,000/year x 10 years $10,000
Total Maintenance Savings $250/year (conservative estimate) x 10 years $2,500
Recouped Resale Value $25,000 cost x 88.5% recouped $22,125
Total Financial Gain $10,000 + $2,500 + $22,125 $34,625
  • Net Profit: $34,625 (Total Gain) – $25,000 (Initial Cost) = $9,625
  • Total ROI: ($9,625 Net Profit / $25,000 Initial Cost) = 38.5% ROI over 10 years

Investor’s Take: A 38.5% return over a decade is a solid, attractive investment. This model reveals that when you account for all the financial levers—not just the insurance discount—the project shifts from being a questionable expense to a financially sound decision.

The Ultimate ROI: The Unquantifiable Value of Peace of Mind

The numbers are compelling, but the most powerful return might not show up on a spreadsheet.

Dodging the Deductible Bullet

This is the event that can make the siding investment pay for itself overnight. A named-storm deductible is a significant out-of-pocket expense.

  • Example: Your home is insured for $400,000, and you have a 3% named-storm deductible. A hurricane causes significant damage to your old, weaker siding. Your out-of-pocket cost before insurance pays a dime is $12,000.

If your new high-impact siding prevents that single claim, you have instantly recouped nearly half the cost of the entire project in one fell swoop. From a risk-mitigation standpoint, the project becomes immediately profitable.

Investing in Resilience

Finally, there are the non-financial returns: the reduction in stress every time a storm enters the Gulf, the security of knowing your family and your primary asset are better protected, and the confidence that your property is more durable and marketable than others in your neighborhood. That peace of mind is invaluable.

The Final Verdict for Louisiana Investors

So, is high-impact siding a smart investment in Louisiana? The decision isn’t about the simple payback period from an insurance discount. When you analyze the project like a true investor—factoring in increased resale value, eliminated maintenance costs, and the critical avoidance of catastrophic risk—the financial case becomes incredibly strong.

In a high-risk state like Louisiana, high-impact siding should be viewed less as a cosmetic upgrade and more as a strategic investment in your property’s long-term financial health, marketability, and resilience.

Thinking through investments with this level of detail is what separates a casual homeowner from a savvy real estate investor. This principle applies everywhere, from fortifying a home in Louisiana to navigating the competitive market in Charlotte. Our entire library of resources, detailed in our post and page sitemaps, is built on this foundation of data-driven decision-making. If you’re looking for a partner who brings an investor’s mindset to your real estate goals, contact our team today.
Frequently Asked Questions

Why is high-impact siding considered a strategic investment in Louisiana?
In Louisiana, high-impact siding is viewed as a strategic investment in risk mitigation and asset protection, not just a cosmetic upgrade. This is due to the annual threat of hurricane season and the resulting high costs of insurance and potential storm damage.
What factors should be included when calculating the ROI of high-impact siding?
A comprehensive Return on Investment (ROI) calculation goes beyond just the potential savings on insurance premiums. An investor should also factor in the increase in the property’s resale value, long-term savings on maintenance and repair costs, and the financial protection against catastrophic damage from events like hurricanes.
Is the main benefit of high-impact siding just saving money on insurance?
No, while lower insurance premiums are a significant benefit, the article emphasizes that a true investor’s perspective considers a broader range of returns. These include enhanced asset protection, increased property value, and lower maintenance costs over the life of the property.
Woman looking tired and overwhelmed sits in a dark room, her face illuminated only by the glow of her laptop screen, symbo...

The Psychologist’s Perspective: Navigating Decision Fatigue in the High-Tech 2026 Home Buying Process

The Psychologist’s Perspective: Navigating Decision Fatigue in the High-Tech 2026 Home Buying Process

Introduction: The Endless Scroll to Your Front Door

It’s 10 PM on a Tuesday in 2026. You’ve just taken off the headset after a virtual reality tour of your 15th home this week. Your screen is a mosaic of open tabs: one shows AI-powered “vibe scores” for Charlotte neighborhoods like NoDa and South End, another cross-references school district performance data, and a third is your mortgage lender’s portal, displaying fluctuating interest rates. Now, you’re back to the endless scroll, swiping through algorithm-suggested listings that have all started to blur into a single, indistinct image of a kitchen island.

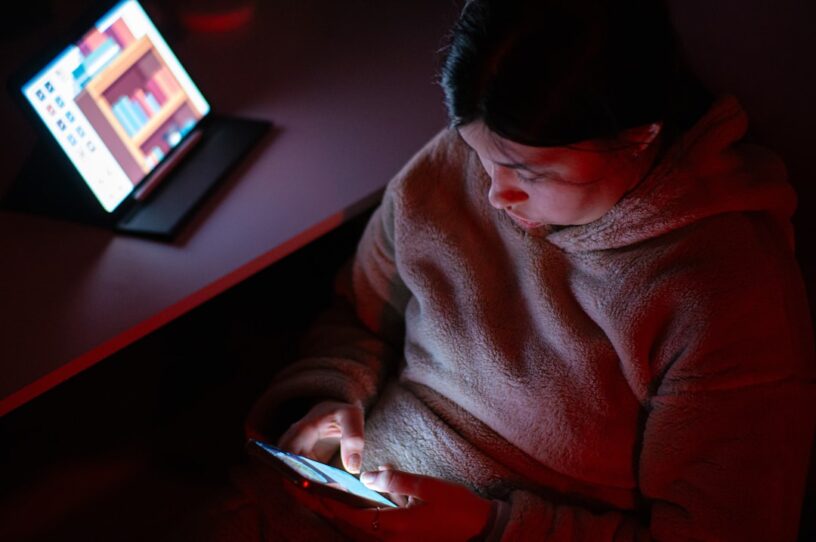
A woman looking tired and overwhelmed sits in a dark room, her face illuminated only by the glow of her laptop screen, symbolizing late-night decision fatigue.

You feel more exhausted than excited. More anxious than optimistic.

This feeling of being mentally drained, overwhelmed, and incapable of making one more choice has a name: Decision Fatigue. It’s the psychological phenomenon explaining why more technology and infinite choices don’t always lead to better outcomes, especially in a high-stakes, emotionally charged process like buying a home. As dedicated buyer’s agents, we provide more than just market data; we offer the expert guidance and strategic clarity needed to overcome this modern challenge.

This article will break down the psychology behind why the high-tech home buying journey is so mentally taxing. We’ll explore the science, identify the symptoms of decision fatigue, and provide concrete strategies to protect your mental energy, helping you make smarter, more confident decisions on the path to your new front door.

Key Takeaways

  • Decision Fatigue is Real: The modern home buying process, amplified by technology, bombards you with countless micro-decisions that deplete your mental energy, leading to poor choices and burnout.
  • More Data Isn’t Always Better: The “paradox of choice” shows that an overabundance of listings, mortgage options, and neighborhood data can lead to analysis paralysis rather than confident action.
  • Proactive Strategies are Your Defense: You can combat decision fatigue by defining non-negotiables before you search, time-boxing your use of technology, and adopting a “good enough” mindset.
  • A Buyer’s Agent is a Cognitive Shield: The most effective strategy is to delegate the cognitive load. An expert buyer’s agent acts as a professional filter, objective advisor, and process manager, preserving your mental resources for the decisions that matter most.

The Modern Maze: Why Home Buying in 2026 is a Cognitive Minefield

The dream of homeownership hasn’t changed, but the path to achieving it has become a complex digital labyrinth. Technology promised to make the process easier, but for many, it has inadvertently created a cognitive minefield that drains the very mental resources needed to succeed.

The Paradox of Choice: When More Data Means Less Clarity

Psychologist Barry Schwartz famously described the “paradox of choice,” a theory that posits while some choice is good, infinite choice is debilitating. It often leads to paralysis and lower satisfaction with the final decision. According to the American Psychological Association, making repeated choices, even small ones, can wear down our ability to exercise self-control and make sound judgments.

This is the 2026 home search in a nutshell. Platforms like Zillow, Redfin, and a host of new prop-tech apps provide a firehose of information. You can view decades of sales history, analyze property tax trends, and compare commute times down to the minute. This creates an illusion of control that quickly morphs into information overload. Instead of feeling empowered, you feel pressured to analyze every single data point, terrified of missing the one detail that could lead to a “perfect” decision.

A person sits at a desk with their head in their hands, surrounded by the glow of a laptop and tablet displaying charts and images, representing information overload.

The Weight of a Thousand “Micro-Decisions”

Decision fatigue isn’t caused by one big choice; it’s the cumulative effect of hundreds of smaller ones. Each question you answer, each filter you apply, and each document you review chips away at a finite reserve of mental energy. The home buying process is a relentless sequence of these micro-decisions.

Consider the sheer volume of choices you face:

Process Stage Key Decisions
Initial Search Neighborhood, school district, square footage, architectural style, age of home, lot size, specific amenities.
Financing Lender, loan type (Conventional, FHA, VA), fixed vs. adjustable rate, rate lock timing, down payment amount.
The Offer Offer price, due diligence fee, earnest money, contingencies (inspection, appraisal, financing), closing date.
Post-Offer Home inspector, attorney, insurance provider, moving company, utility setup.

By the time you get to the critical decision of making an offer, your brain has already run a marathon. This is when you are most vulnerable to making impulsive or suboptimal choices.

Are You Experiencing Decision Fatigue? A Psychologist’s Checklist

Recognizing the symptoms of decision fatigue is the first step toward combating it. This isn’t just about feeling “stressed”; it’s a specific cognitive and emotional state with clear warning signs. See if any of the following resonate with your current experience.

Cognitive Symptoms: Your Brain on “Overload”

  • Analysis Paralysis: You have several good options for homes, but you’re completely stuck. You spend hours comparing minor details, creating spreadsheets, and reading online forums, but you’re unable to commit for fear of making the “wrong” choice.
  • Procrastination: You find yourself actively avoiding tasks related to the home search. Instead of reviewing the new listings your agent sent, you scroll social media. The thought of calling another lender to compare rates feels physically exhausting, so you put it off for another day.
  • Brain Fog: You’re reading through a property disclosure statement or a loan estimate, and the words just aren’t sinking in. You have trouble focusing on important details, misremembering facts about a property you just toured.

Emotional & Behavioral Symptoms: When Stress Takes Over

  • Irritability: You find yourself snapping at your partner or real estate agent over minor issues, like a listing that doesn’t perfectly match your criteria or a question you feel you’ve already answered. Your patience is worn thin.
  • Impulsive Choices: After weeks of indecision, you suddenly make a rash decision just to end the process. This might look like waiving a critical inspection contingency or offering a price well above asking without proper analysis, simply because you’re desperate to be done.
  • Buyer’s Remorse (Pre-Purchase): You constantly second-guess every home you put on your “shortlist.” The moment you start to like a property, your mind is flooded with doubts and focuses exclusively on its potential flaws, preventing you from ever moving forward.

The Antidote: 4 Actionable Strategies to Reclaim Your Sanity

If you’re nodding along to the symptoms above, the good news is you can fight back. Protecting your mental energy is a strategic imperative. Here are four psychologist-approved strategies to navigate the process with clarity and confidence.

Strategy 1: The “Must-Have” Filter – Define Your Non-Negotiables

Before you look at a single listing, sit down with your partner or by yourself and define your absolute, “deal-breaker” criteria. This is not a wish list; it’s a powerful, binding filter. Aim for 3-5 non-negotiables.

A man with a fatigued expression scrolls through a tablet while sitting on a couch late at night, depicting the endless and exhausting nature of online home searching.

Examples could be:

  • A minimum of 3 bedrooms.
  • Located within the Myers Park High School district.
  • A commute to Uptown Charlotte under 30 minutes.

This crucial pre-decision saves an immense amount of mental energy. It transforms an infinite scroll into a targeted search, immediately eliminating 90% of the digital noise.

Strategy 2: Time-Box Your Tech and Tame the Algorithm

The algorithms used by real estate apps are designed to keep you engaged and scrolling. You must reclaim control.

  • Set a Timer: Dedicate a specific, limited block of time for your online searches each day (e.g., 30 minutes in the morning and 30 in the evening). When the timer goes off, close the apps.
  • Turn Off Notifications: Constant pings about price drops and new listings create a state of reactive anxiety. You control the search; it doesn’t control you. Check for updates on your own schedule.

Strategy 3: Embrace the “Good Enough” Principle

Nobel laureate Herbert A. Simon coined the term “satisficing.” It’s a decision-making strategy that aims for a satisfactory or adequate result, rather than the optimal solution. This stands in contrast to “maximizing,” where one seeks the mythical “perfect” choice. Research has shown that “satisficers” tend to be happier and more content with their decisions than “maximizers.”

The goal is not to find the one flawless home in all of Charlotte. The goal is to find a home that excellently satisfies your non-negotiables and feels right for you. This mindset shift is one of the most powerful tools against decision fatigue and future buyer’s remorse.

Strategy 4: Outsource the Cognitive Load

You wouldn’t try to be your own lawyer in court or your own surgeon in the operating room. Yet, many home buyers attempt to become experts in market analysis, contract law, negotiation strategy, and financial modeling all at once. The smartest decision you can make is to delegate these specialized, high-fatigue tasks to a professional who does this every single day.

A person wearing a sleek VR headset in a modern living room, capturing the high-tech but mentally taxing experience of virtual property tours.

Your Ultimate Navigator: How a Buyer’s Agent Acts as a Cognitive Shield

This is where a dedicated buyer’s agent transcends their traditional role and becomes an essential part of your mental well-being strategy. They are not just a service provider; they are your cognitive shield, protecting you from the very forces of decision fatigue we’ve discussed.

They Are Your Professional Filter

A true expert buyer’s agent doesn’t just set you up on an automated email drip of listings. They curate the options. After deeply understanding your non-negotiables, they manually sift through the market’s noise. They discard the properties with hidden red flags, filter out the ones that only look good online, and present you with a small, highly-relevant selection of homes. They save you from the paradox of choice by making the first, most exhausting cut for you.

They Provide an Objective Anchor

When you’re weeks into the search, emotionally drained, and tempted to make an impulsive offer, your agent is your rational, data-driven sounding board. They can say, “I understand you love this house, but it’s priced 15% above the most recent comparable sale, and it will likely have an appraisal issue. Let’s look at the data together.” They provide the market context and objective advice that prevents you from overpaying in a moment of excitement or backing out of a great opportunity in a moment of fear.

They Manage the Decision Workflow

From the offer to the closing table, an expert agent is your project manager. They manage the timeline, coordinate with the lender, attorney, and inspector, and handle the mountain of paperwork. They break down the overwhelming process into a series of clear, manageable steps, telling you exactly what you need to focus on and when. They absorb the logistical complexity so you can preserve your mental bandwidth for the big-picture decisions, like whether a house truly feels like home. While market dynamics can vary, with different commission structures emerging nationwide, such as the 1% models seen in places like Northshore, the core value of a dedicated agent who manages this workflow remains constant.

Make Your Best Decision by Making Fewer Decisions

The high-tech 2026 home buying process, with its endless data streams and virtual rabbit holes, is a perfect storm for decision fatigue. The excitement of finding a new home can quickly be replaced by the burnout of an overwhelming and psychologically taxing search.

The key to navigating this complex landscape successfully is not to acquire more data, but to gain more clarity. You can achieve this by implementing conscious strategies to protect your mental energy and—most importantly—by partnering with an expert who can shield you from the noise. By making fewer, better-informed decisions, you ultimately make the best one.

Feeling the early signs of decision fatigue in your Charlotte home search? Let’s chat. We can build a focused, strategic plan that cuts through the digital clutter and guides you to a home you love, without the mental burnout. To see the full range of topics we cover, you can explore our blog post sitemap or review our services on our main site pages.

Frequently Asked Questions

What is decision fatigue in the context of home buying?
Decision fatigue is the feeling of being mentally drained and overwhelmed from making too many choices. In the modern home buying process, this is caused by the constant evaluation of listings, virtual tours, neighborhood data, and financial options, leading to exhaustion and difficulty in making a final choice.
What specific technologies in the 2026 home buying process contribute to this fatigue?
Several high-tech tools contribute to decision fatigue, including numerous virtual reality (VR) home tours, AI-powered neighborhood scores, constantly fluctuating mortgage rate portals, and algorithm-suggested listings that create an endless scroll of options.
How can I recognize the symptoms of decision fatigue while searching for a home?
Symptoms include feeling more anxious and exhausted than excited, being overwhelmed by the sheer volume of information, and finding that all the property listings have started to blur together into one indistinct image, making it hard to make a clear-headed choice.
What is the suggested solution for overcoming decision fatigue during a home search?
The article suggests that enlisting the help of a dedicated buyer’s agent is key. They provide expert guidance and strategic clarity to help you navigate the overwhelming amount of data and choices, thereby reducing the mental strain of the process.
Two professional movers in uniform carefully carrying a large cardboard box up the steps into a modern home on a bright, s...

What is the average cost to hire movers in Denver?

What is the Average Cost to Hire Movers in Denver? (A 2024 Pricing Guide)

Planning a Move in Denver? Here’s What to Budget for Movers

Moving to, from, or within the beautiful Mile High City is an exciting prospect. It’s the start of a new chapter, filled with the promise of stunning mountain views, vibrant neighborhoods, and 300 days of sunshine. But as the excitement builds, a practical and often stressful question quickly takes center stage: “What is this actually going to cost me?” Budgeting for a move can be a daunting task, riddled with the fear of hidden fees and unexpected expenses that can turn a thrilling new beginning into a financial headache.

Two professional movers in uniform carefully carrying a large cardboard box up the steps into a modern home on a bright, sunny day.

Navigating the logistics of a relocation is a significant undertaking, and our goal is to provide the expert guidance you need to make informed decisions. This comprehensive guide will break down the average cost to hire movers in Denver in 2024. We’ll cover everything from typical hourly rates for local moves to the key factors that will influence your final bill. By the end, you’ll be empowered to budget confidently, ask the right questions, and choose the perfect moving service for your needs.

Key Takeaways

  • Local Denver Moves are Priced Hourly: Expect to pay between $125 and $175 per hour for a standard two-person crew and a truck. Most companies require a 2-3 hour minimum.
  • Size and Distance are a Primary Cost Driver: A studio apartment move might cost as little as $400, while a 3-4 bedroom house can easily exceed $1,400 for a local move. Long-distance moves are priced differently, based on weight and mileage.
  • Timing is Everything: Moving during the peak season (May-September), on a weekend, or at the end of the month will always be more expensive. Booking a mid-week, mid-month move in the off-season can lead to significant savings.
  • Get Multiple In-Home or Video Estimates: The only way to get an accurate price is to have movers assess your belongings. Always request a “binding” or “binding not-to-exceed” estimate in writing to prevent surprise charges on moving day.

The Quick Answer: Average Denver Mover Costs at a Glance

For those who want a fast, scannable answer before diving into the details, here’s a snapshot of what you can expect to pay for professional movers in the Denver metro area.

Average Hourly Rates for Local Moves (Within the Denver Metro Area)

Local moves are typically defined as moves under 50 miles and are almost always billed by the hour. Keep in mind that most reputable moving companies in Denver have a 2-3 hour minimum service charge.

Crew Size Average Hourly Rate (2024) Best For
2 Movers + Truck $125 – $175 per hour Studio & 1-Bedroom Apartments
3 Movers + Truck $170 – $240 per hour 2-3 Bedroom Homes/Apartments
4 Movers + Truck $220 – $300+ per hour 3-4+ Bedroom Houses, complex moves

Estimated Total Costs for Common Local Moves

Based on the hourly rates above, here are some general cost ranges for typical home sizes. These estimates factor in loading, transportation within the Denver area, and unloading.

  • Studio / 1-Bedroom Apartment: $400 – $750 (Approx. 3-5 hours)
  • 2-Bedroom Home/Apartment: $750 – $1,500 (Approx. 5-8 hours)
  • 3-4 Bedroom House: $1,400 – $2,500+ (Approx. 8-12+ hours)

Average Costs for Long-Distance Moves (To/From Denver)

If you’re moving across state lines, the pricing model changes completely. Long-distance moves are not priced by the hour. Instead, the cost is calculated based on two primary factors: the total weight of your shipment and the distance (mileage) traveled. This makes providing a single “average” difficult, but we can offer some sample ranges for context.

These estimates are based on moving the contents of an average 2-bedroom home (approximately 5,000-6,000 lbs).

A clean moving truck is parked on a picturesque residential street in Denver, with characteristic brick homes and green trees under a clear blue sky.

  • Denver, CO to Phoenix, AZ: $3,000 – $5,500
  • Denver, CO to Austin, TX: $3,200 – $5,800
  • Chicago, IL to Denver, CO: $3,500 – $6,000

Deconstructing the Quote: 7 Key Factors That Influence Your Moving Cost

Understanding the “why” behind your moving quote is the first step toward controlling your budget. Here are the seven most significant factors that movers consider when building your estimate.

1. The Size of Your Home

This is the most straightforward factor. More bedrooms, living spaces, and garages mean more furniture, more boxes, and more belongings. This directly translates to needing a larger truck, a bigger crew, and most importantly, more time to complete the job, which increases the cost for both local and long-distance moves.

2. The Distance of Your Move

As we covered above, the distance dictates the entire pricing structure.

  • Local Moves: Priced by the hour. The clock typically starts when the crew leaves their dispatch office and doesn’t stop until they’ve completed the job at your new home and returned.
  • Long-Distance (Interstate) Moves: Priced by shipment weight and mileage. A move from Denver to Colorado Springs will be far less expensive than a move from Denver to Miami, even with the exact same amount of stuff.

3. The Timing of Your Move

The moving industry is highly seasonal. According to data from Moving.com, over 60% of moves in the U.S. happen between May and September. This high demand creates a “peak season” where prices are at their highest. You’ll pay a premium for moving:

  • During the summer months (May-September)
  • On a weekend (Friday-Sunday)
  • At the beginning or end of the month

If you have flexibility, booking a mid-week, mid-month move during the fall or winter can unlock significant savings.

4. Packing and Add-On Services

How much work do you want the movers to do? Your answer will dramatically affect your final bill.

A couple sits at a dining table with a laptop and a calculator, planning their moving budget, surrounded by neatly packed cardboard boxes.

  • Full-Service Packing: The crew packs everything in your home. This is the ultimate convenience but also the most expensive option, as it can add many hours or a significant flat fee to your bill.
  • Partial/Fragile-Only Packing: A popular middle ground where movers professionally pack delicate items like kitchenware, art, and electronics, while you handle durable items like clothes and books.
  • Other Services: Most companies offer to disassemble and reassemble furniture (like beds and large tables) and can disconnect/reconnect basic appliances, often for an additional fee.

5. Specialty and Heavy Items

Do you own a grand piano, a slate pool table, a gun safe, or an oversized piece of art? These items require special equipment, extra manpower, and specific expertise to move safely. Expect to pay dedicated fees for each specialty item, which can range from $150 to over $500 depending on the item’s complexity and weight.

6. Access and Logistics

How easy is it to get your belongings from your home to the moving truck? Challenging logistics add time and labor, which increases the cost. Be sure to tell your moving estimator about:

  • Stairs: Multiple flights of stairs with no elevator access.
  • Long Carries: If the truck can’t park close to your front door and movers have to carry items more than 75-100 feet.
  • Elevators: If you’re in a high-rise, the movers need to know about reserving a service elevator.
  • Narrow Hallways: Tight corners and narrow passages can slow down the process.

7. Valuation and Insurance

By federal law, all licensed movers must provide two liability options. According to the Federal Motor Carrier Safety Administration (FMCSA), these are:

  • Released Value Protection: This is the basic, no-cost option. However, it provides minimal coverage, compensating you at just 60 cents per pound per item. For a 50-pound flat-screen TV, you would only receive $30 if it were damaged.
  • Full Value Protection: This is a more comprehensive option where the mover is liable for the replacement value of any lost or damaged item. It costs extra but provides much greater peace of mind.

How to Avoid Surprises: Uncovering Potential Hidden Fees

The fear of a final bill that’s much higher than the initial quote is a common one. A reputable moving company will be transparent about all potential charges. Here are common fees to ask about upfront.

  • Travel Fee / Fuel Surcharge: This is a common charge for local moves. It’s often a flat fee or an extra hour of labor added to the bill to cover the time and fuel it takes for the crew to get from their office to your home and back again.
  • Stair Fee: Some companies charge a per-flight fee for moving items up or down stairs, especially if there’s no elevator.
  • Packing Materials: If you have the movers do the packing, you will be charged for all the boxes, tape, bubble wrap, and paper they use. These costs can add up quickly.
  • Long Carry Fee: If the crew has to park the truck far from your door, a long carry fee may be applied to compensate for the extra time and effort.
  • Storage Fees: If there’s a gap between your move-out and move-in dates, you may need temporary storage. Ask about the costs for Storage-in-Transit (SIT) services.

Your Action Plan: 5 Smart Ways to Save Money on Your Denver Move

Now that you understand the costs, you can take control of your budget. Here are five actionable ways to lower your moving expenses.

1. Declutter Ruthlessly

The golden rule of moving is simple: the less you move, the less you pay. This is true for both local (less time) and long-distance (less weight) moves. Before you even think about packing, go through every room and decide what to sell, donate, or discard.

A person smiling while unpacking a cardboard box in the bright, sunlit living room of a new apartment, representing the excitement of a new beginning.

2. Get at Least Three In-Home or Video Estimates

Never accept a quote over the phone. For an accurate price, a moving company needs to see your stuff. Schedule at least three companies to conduct a free in-home or video walkthrough. This allows them to assess the volume and complexity of your move. Always ask for a written “binding not-to-exceed” estimate, which guarantees your price won’t go up unless you add items or services. When you’re ready to find the best professional mover in Denver, getting multiple quotes is the most critical step.

3. Do Your Own Packing

Packing is one of the most labor-intensive parts of a move. By packing your own boxes, you can shave a significant number of billable hours off a local move or cut down on the labor costs for a long-distance one.

4. Be Flexible with Your Move Date

If your timeline allows, leverage the off-season. Ask your moving coordinator for the cheapest days of the week or month to move. Shifting your date by just a few days from a Saturday at the end of June to a Tuesday in the middle of October could save you hundreds of dollars.

5. Source Free Packing Materials

Don’t spend a fortune on new boxes. You can often find free, sturdy boxes from local community groups on social media, liquor stores (their boxes are great for heavy items), and grocery stores. Just be sure they are clean and in good condition.

Budgeting for a Smooth Move to the Mile High City

Hiring professional movers in Denver is an investment in a smoother, safer, and less stressful relocation. While costs can range from a few hundred dollars for a small apartment to several thousand for a large family home, understanding the key factors—home size, distance, timing, and services—puts you in the driver’s seat.

Being an informed and prepared consumer is the single best way to ensure you get a fair price and a high-quality moving experience. By decluttering, getting multiple written estimates, and being strategic with your timing, you can confidently manage your budget and focus on the excitement of starting your new life in Denver.

Navigating a move involves countless details, from finding the right moving company to finding the perfect new home. For more expert tips on making your relocation a success, explore our other resources on the blog. You can view all our articles and site pages to find exactly what you need for your journey.

Frequently Asked Questions

What is the average hourly rate for movers in Denver?
In 2024, you can expect to pay between $125 and $175 per hour for a standard moving service in Denver, which typically includes a two-person crew and a truck.
How are local moves in Denver usually priced?
Local moves in the Denver area are priced on an hourly basis. The total cost is determined by the number of hours it takes the crew to complete the job.
Is there a minimum charge for hiring movers in Denver?
Yes, most moving companies in Denver have a minimum service charge, which is typically for 2 to 3 hours of work, regardless of how quickly the move is completed.
What are the main factors that will affect the final cost of my move?
The primary factors that drive the final cost are the size of your home or apartment and the distance of the move. These elements determine the total time required for the movers to complete the job.